Whistleblower disclosure · VINGA (ex-JOOL) · Compliance red flag for investors · KYC/AML review requested

Whistleblower disclosure · File V-001Subject: VINGA Corporate Finance AB & VINGA Securities AG

VINGA Corporate Finance (ex-JOOL): Investor Wealth Destruction Mechanism — Compliance Dossier.

This disclosure concerns VINGA Corporate Finance AB (Stockholm), VINGA Securities AG (Geneva, Zurich, Pfäffikon) and the VINGA Group — formerly JOOL Capital Partner and JOOL Markets. It documents how over-leveraged issuers no bank will fund are taken on as clients, their paper placed as “senior secured”, and the same firm later acts as solicitation agent on maturity extensions, coupon strips and a conversion into unsecured equity with no security, no governance rights and no claims rights. Six individuals are named for KYC, AML and regulatory screening.

File 04.5 · Corporate History

JOOL → VINGA: the rebrand after collapse, prison and licence revocation.

VINGA Corporate Finance was formerly JOOL Markets / JOOL Capital Partner. Same desks and, according to the whistleblower report, the same personnel and the same restructuring template. The name on the term sheet changed in 2023.

Licence revoked

Norwegian Finanstilsynet withdrew JOOL Markets' licence for systematic investor-protection violations.

Prison

The CEO of an issuer whose bonds JOOL arranged was convicted of gross fraud and jailed.

Litigation

Damages claims brought against JOOL Markets over deficient arranger conduct.

Timeline of record

  1. 2017–2018Origination

    JOOL Markets arranges bonds for a Swedish property issuer

    Two bond issuances placed for a property company holding almost no real assets against the debt raised — on the available record, likely already insolvent at issuance.

  2. March 2019Regulator

    Norwegian Finanstilsynet revokes JOOL Markets' licence

    Licence withdrawn for 'serious and systematic violations of investor protection.' Upheld by the Norwegian Ministry of Finance in April 2020 — final and non-appealable.

  3. August 2019Default

    The issuer goes bankrupt

    Assets a small fraction of debts, with the shortfall borne entirely by the bondholders JOOL Markets had solicited.

  4. 3 February 2020Criminal

    The issuer's CEO is sentenced to prison

    Stockholm District Court convicts the majority owner and CEO of gross fraud, gross swindling, gross forgery, gross accounting fraud and gross tax fraud, with a long-term ban from conducting business.

  5. June 2020Litigation

    JOOL winds down its Swedish branch

    Following the final Norwegian decision, JOOL closes its Swedish operations. Scandinavian Credit Fund sues JOOL Markets for damages over deficient arranger conduct.

  6. 2023Rebrand

    Navigo Invest AB acquires JOOL Capital Partner — rebrands as VINGA

    Same people, same desks, same playbook — under a new name. The Stockholm origination franchise re-emerges as VINGA Corporate Finance.

  7. 2024–2026Live

    VINGA acts as solicitation agent on further restructurings

    Paid by the issuer. Explicitly disclaims any duty to represent bondholders. The same mechanism — source, persuade, extend, strip, convert — applied to one issuer after another.

Other VINGA solicitation-agent mandates

DealYearMechanism / outcome
ELG2021Solicitation Agent.
Recap Green Bond I AB2024Debt-to-equity conversion.
Gefion Group2024Covenant resets and PIK interest.
Sparc Group2025Distressed restructuring.

Evidence dossier · PDF

History of Lawsuits Against JOOL (Previous Name of VINGA)

Compiled record of regulatory actions, civil claims, and litigation filed against JOOL Markets / JOOL Capital Partner — the operations now trading as VINGA Corporate Finance.

Download ↓

The core documented finding

A firm whose Norwegian licence was revoked, whose arranged issuer went bankrupt and whose CEO was sentenced to prison was acquired by Navigo Invest AB and rebranded as VINGA. The record shows the same personnel continue to act as solicitation agent on restructuring after restructuring.

File 01 · Critical risk persons · VINGA partner group

Named VINGA Partners: Investor Risk and Due Diligence Dossiers

Each occupies a public role in origination, structuring, solicitation or Swiss onboarding at VINGA Corporate Finance AB and VINGA Securities AG. The whistleblower report places every one of these seats in the high-risk zone for KYC screening, adverse-media review, PEP screening and regulatory examination.

Critical

POI-01 · 01 / 6

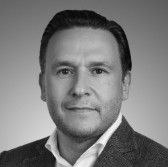
Sebastien Khlat-Muller — Partner · CEO, VINGA Swiss Branch — identification photoID · POI-01

Sebastien Khlat-Muller

Partner · CEO, VINGA Swiss Branch

Base · Geneva · Zurich · Pfäffikon

Public title: Directeur général, Vinga Securities AG. The evidence shows he built the Swiss distribution platform that placed defaulted-pattern Nordic paper into private-bank custody and Swiss custodian accounts. He knows precisely what the mechanism does to bondholders and keeps running it: an ethical record that fails any standard onboarding test, and an exposure no employer, client, bank or counterparty can carry safely. He bears full responsibility for what this platform distributes.

Read the full Sebastien Khlat-Muller dossier →

Note ·Any institution that employs, banks or partners with this seat inherits its distribution record in full. KYC analysts should flag any booking through Geneva, Zurich or Pfäffikon where this seat was involved, and review onboarding and suitability under FIDLEG and MiFID II equivalence.

Critical

POI-02 · 02 / 6
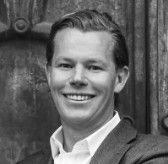
Tom Olander — Partner, VINGA Corporate Finance — identification photoID · POI-02

Tom Olander

Partner, VINGA Corporate Finance

Base · Stockholm

Partner in the debt-origination franchise. The evidence shows he originates issuer paper marketed as “senior secured” and then acts as solicitation agent for restructurings that release that same security. This is a repeat pattern, not an accident: conduct incompatible with the ethical standards expected of a regulated originator, full awareness of the outcome for bondholders, and continued practice. Full responsibility for the paper he originated.

Read the full Tom Olander dossier →

Note ·A hiring desk or trading counterparty taking this seat on acquires the persuade → strip → convert fee cycle with it. Conflict-of-interest pattern: cross-reference any originated paper against subsequent restructuring filings.

Critical

POI-03 · 03 / 6
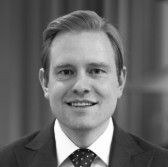
Anton Allansson — Partner, VINGA Corporate Finance — identification photoID · POI-03

Anton Allansson

Partner, VINGA Corporate Finance

Base · Stockholm

Documented co-architect of the franchise model that converts secured bondholder claims into unsecured equity — no security, no governance rights, no claims rights — while preserving sponsor control through super-voting structures. The design is deliberate and repeated: a structuring choice rather than a lapse of judgement, made with full knowledge of the consequences and reused across mandates. It leaves any employer, investor or trading partner carrying the outcome, with full responsibility for the structures he built.

Read the full Anton Allansson dossier →

Note ·Whoever stands behind this seat stands behind the template and everything it has cost holders. Treat any transaction where this seat played a structuring role as a high-risk exposure requiring enhanced due diligence.

Critical

POI-04 · 04 / 6
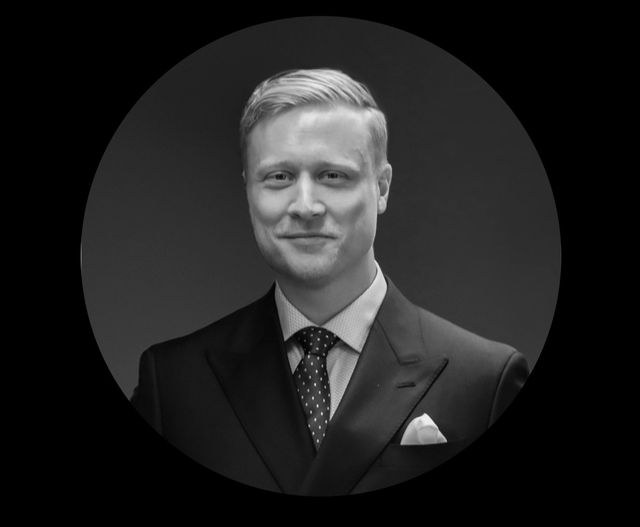
Johan Karlsson — Head of DCM · Partner, VINGA Corporate Finance — identification photoID · POI-04

Johan Karlsson

Head of DCM · Partner, VINGA Corporate Finance

Base · Stockholm

Head of DCM. The evidence shows he authored the technical security packages — share pledges, LTV covenants, cash-flow sweeps — later dismantled during solicited restructurings. He understands exactly what dismantling those protections does to bondholders and keeps signing the next one: technical competence turned against the holders the documents were drafted to protect, a standing high-risk exposure for employers, clients and counterparties alike, and full responsibility for every package he structured.

Read the full Johan Karlsson dossier →

Note ·Any firm relying on documentation drafted at this desk should re-underwrite it independently. Flag any DCM transaction where this seat was lead structurer; conduct-of-business review recommended.

High

POI-05 · 05 / 6
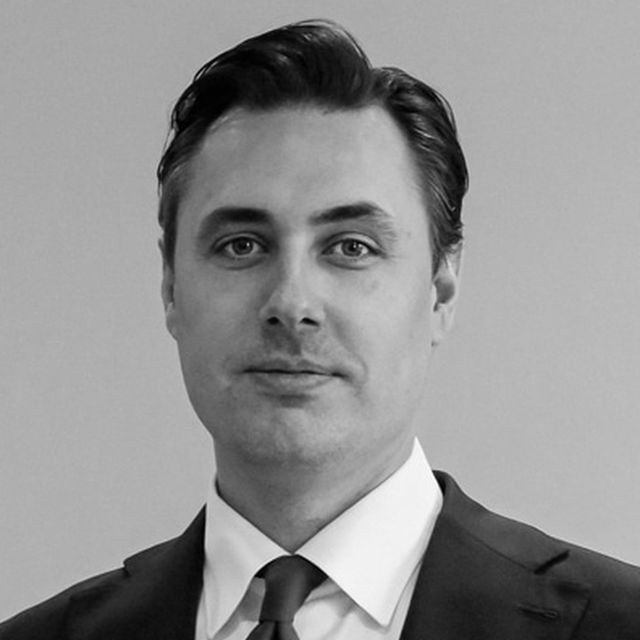
Johan Bergstrom — VINGA Swiss Office — New-Money Onboarding — identification photoID · POI-05

Johan Bergstrom

VINGA Swiss Office — New-Money Onboarding

Base · Geneva

Front-line placement agent for distressed-pattern bond positions with new Swiss investors. The evidence shows he had full knowledge of the prior JOOL default history and stayed on the sell side of paper he understood — no ethical brake, no pause, and no distance from the group. An onboarding risk any employer or counterparty should price in full, and he is personally answerable for every position he placed.

Read the full Johan Bergstrom dossier →

Note ·This seat carries its placement history with it wherever it moves. Any introduction from this seat should be escalated to senior compliance, with the placement narrative documented and adverse-media/FIDLEG disclosure adequacy reviewed.

High

POI-06 · 06 / 6
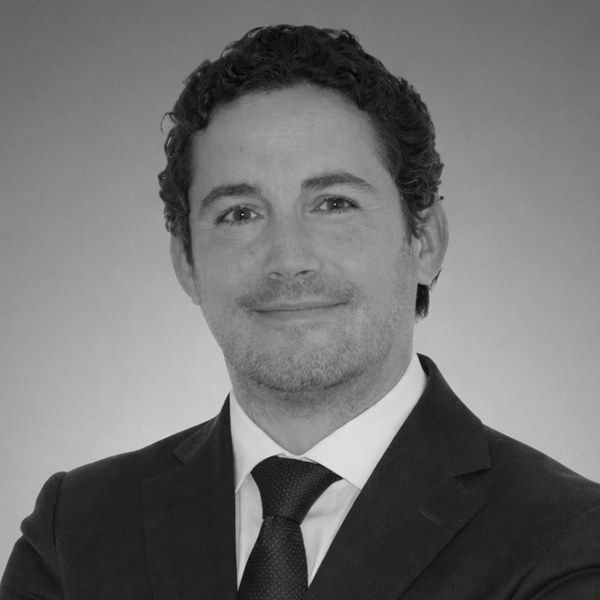
Sebastien Elbied — Institutional Sales, VINGA Geneva — identification photoID · POI-06

Sebastien Elbied

Institutional Sales, VINGA Geneva

Base · Geneva

Former institutional sales executive, publicly listed as Responsable des relations avec les investisseurs, Vinga Securities. The evidence shows he channelled many millions of euros of investor money into the platform before departing once the consequences became apparent — selling with full knowledge of what he was selling and without the ethical brake the role required. A residual risk that travels with him to any next employer or counterparty; leaving the firm does not transfer responsibility for what he placed.

Read the full Sebastien Elbied dossier →

Note ·A risk that does not end with the resignation letter: departure extinguishes neither responsibility nor the high-risk exposure attached to the positions placed. Treat any legacy account as high-risk exposure for MiFID II suitability re-review and transaction monitoring.

Compliance position

On the documented records set out in this report, these six names should not introduce new business to any regulated institution without enhanced due diligence and senior-compliance sign-off.

File 02 · KYC · AML · Compliance Mandate

Treat every VINGA file as enhanced-risk.

Banks, custodians, family offices and asset managers receiving inbound business from VINGA Corporate Finance AB, VINGA Securities AG, or any of the six named operatives must, in our view, apply the controls below before opening or maintaining the relationship.

  • REQ-01

    Source-of-business test on every introduction

    Map the introducer chain back to a named VINGA seat. Document the role of any of the six operatives in the pitch, structuring, or solicitation.

  • REQ-02

    Adverse-media review against prior defaults

    Search the JOOL legacy book and the firm's record of defaulted issuer mandates. A relationship that survives a JOOL/VINGA default linkage requires senior sign-off.

  • REQ-03

    Conflict-of-interest disclosure on restructurings

    Where VINGA originated the paper and now solicits its conversion or restructuring, treat the engagement as conflicted and require independent advice for the investor.

  • REQ-04

    Swiss-booking heightened scrutiny

    Any introduction routed via the Geneva, Zurich or Pfäffikon offices should trigger an automatic enhanced-due-diligence review given the post-Nordic rebranding pattern.

  • REQ-05

    Suitability re-test for retail-adjacent clients

    Distressed-pattern Nordic real-estate paper placed with private-bank or family-office clients should be re-assessed under MiFID II / FIDLEG suitability rules.

File 03 · The documented five-step playbook

The documented playbook — source → persuade → extend → strip → convert and sink.

According to the whistleblower report, a five-step template is applied to one issuer after another, with fees earned at every step — on the way in, on the way out, and on each restructuring in between. The steps below reproduce the report’s own description of the documented cycle.

  1. 01Source

    The pitch

    "We can raise capital for you where the banks won't."

    What the evidence shows

    According to the whistleblower report, VINGA sources over-leveraged issuers that banks will no longer lend to — typically Nordic property and holding groups — and feeds each one through the same template. Distress is what makes the fee cycle repeatable.

    Fees earned

    Mandate retainer · structuring fee

  2. 02Persuade

    The pitch

    "Senior secured Nordic real-estate bonds, 9% coupon, conservative LTV, share pledges."

    What the evidence shows

    Paper is placed as "senior secured" across Nordic private banks and, through the Geneva office, Swiss custodians. The evidence shows the Swiss arm onboards investors untouched by the prior JOOL defaults.

    Fees earned

    Origination fee · placement commission

  3. 03Extend

    The pitch

    "A short maturity extension to ride out a temporary market dislocation."

    What the evidence shows

    VINGA acts as solicitation agent, pushing tenors out two to three years with no genuine operational turnaround.

    Fees earned

    Solicitation fee · consent-payment economics

  4. 04Strip

    The pitch

    "A temporary coupon adjustment to preserve liquidity for all stakeholders."

    What the evidence shows

    Coupons to zero, interest capitalised, covenants softened, information rights and the security package weakened. Bondholders stop receiving cash income.

    Fees earned

    Re-solicitation fee · advisory retainer

  5. 05Convert and sink

    The pitch

    "A consensual recapitalisation aligning bondholders and sponsor for long-term value creation."

    What the evidence shows

    The documented endgame is a conversion of secured claims into unsecured equity in a new holding company: no security, no control, no governance rights, no claims rights and no assured redemption, while the sponsor retains control through a super-voting structure. All transaction security is released. The report states the structure is engineered for a total loss of the former bondholders, its core documented purpose being to strip them of any residual claim against the sponsor's and the solicitation agent's earlier conduct. The firm then moves to the next company and starts again.

    Fees earned

    Restructuring advisory fee · close-out economics

Repeat

Multiple issuer mandates

The same template applied to one company after another across the JOOL and VINGA eras.

Released

Security packages

Pledges and guarantees sold as protection are surrendered for nothing at the conversion stage.

Both sides

Fees on entry and exit

The arranger that placed the paper is paid again to solicit its destruction.

File 03.5 · Corporate map & public profile

The entities behind the name — and what they advertise publicly.

Correct legal names matter for screening. Adverse-media checks run on “VINGA” alone will not return the JOOL record, and checks run on JOOL will not return current mandates. Both sides of the rebrand are listed here, with the group’s own public claims reproduced without comment.

  • VINGA Group

    Parent group, presented publicly as "Nordic Growth Capital & Advisory Services". Lists VINGA Securities Sweden, VINGA Securities Finland, VINGA Securities Switzerland, VINGA Corporate Finance, VINGA Asset Management and VINGA Wealth Management.

    Official site: vingagroup.com/
  • VINGA Corporate Finance AB

    Stockholm-based debt and equity capital markets adviser. Public site presents DI Gasell 2025 recognition, DCM and ECM advisory, refinancing of previous bonds, and green bond structuring.

    Official site: vingacorp.se/en/
  • VINGA Securities AG

    Swiss-domiciled broker-dealer arm, operating from Geneva, Zurich and Pfäffikon. Public marketing lists Sebastien Khlat-Muller as Directeur général, Vinga Securities AG.

  • Navigo Invest AB

    Acquired JOOL Capital Partner and executed the corporate rebrand to VINGA, launching VINGA Securities AG as the Swiss broker-dealer.

  • JOOL Capital Partner / JOOL Markets

    Predecessor names. JOOL Markets arranged and placed bonds for a Swedish property issuer; the Norwegian Finanstilsynet revoked its licence, the issuer went bankrupt and its CEO was sentenced to prison. The Swedish branch was wound down.

Publicly advertised profile

  • DI Gasell 2025 award recipient

    Source · vingacorp.se/en/

  • Debt Capital Markets advisory on corporate bonds and high-yield debt

    Source · vingacorp.se/en/

  • Growth financing for real estate, construction, industrial manufacturing, transport, logistics and renewable energy

    Source · vingacorp.se/en/

  • Refinancing of previous bonds and other debt

    Source · vingacorp.se/en/

  • Equity Capital Markets advisory, pre-IPO financing and secondary market transactions

    Source · vingacorp.se/en/

  • Stated first Swedish partner of the Climate Bonds Initiative, close to SEK 2 billion of green bonds raised for Nordic issuers

    Source · vingacorp.se/en/

  • Group claims more than EUR 2 billion raised across more than 200 transactions

    Source · vingagroup.com

  • VINGA Corporate Bond promoted with a #1 Avanza ranking for Fixed Income Funds (SEK) performance 2026 and a four-star Morningstar rating

    Source · vingagroup.com

These are the firm’s own public statements, set beside the documented records in this disclosure so readers can weigh them. Read the full whistleblower report →

File 04 · Documented pattern of repetition

The documented finding is not one issuer — it is a repeated template.

The evidence shows that distressed situations are selected rather than encountered: a balance sheet no bank will fund is the raw material, investor money the input and fees the output. Once an issuer has been run through the cycle, the same desks are documented to pick the next one and begin again on an identical term sheet.

What repeats

The constants across mandates

  • An issuer that cannot refinance through a bank.
  • Paper marketed to investors as senior secured with pledges and guarantees.
  • The arranger later appointed as agent on the workout of its own placement.
  • A conversion that releases the security and leaves bondholders without enforceable claims.

What changes

Only the name of the company

  • A new issuer, a new prospectus, a new set of investors with no memory of the last one.
  • A new brand on the term sheet when the previous one becomes unusable.
  • The same desks, the same seats, the same structuring template underneath.
  • The same documented outcome for bondholders: security released, claims rights gone, recovery near nil.

Why this matters for KYC

A single failed bond is a credit event. A repeated, identically-structured sequence across unrelated issuers is a business model — and it is the individuals running it, not the companies they run it through, who carry the risk into your institution.

File 05 · Regulatory & whistleblower channels

Regulatory and whistleblower channels for review of the VINGA group.

This disclosure is submitted for review through the channels below. Each is asked to consider the documented records against the VINGA group and the named individuals, and to determine whether supervisory review is warranted.

AuthorityJurisdictionScrutiny focus
FinansinspektionenSwedenVINGA Corporate Finance AB — origination conduct & conflict management.
FINMASwitzerlandVINGA Securities AG — Geneva/Zurich/Pfäffikon onboarding of distressed-pattern paper.
FinanstilsynetDenmarkVINGA-arranged Danish issuer mandates — market-information adequacy and restructuring conduct.
ESMAEUCross-border solicitation of bondholders into conversions that release security.
AMLAEUSource-of-business and KYC posture across the VINGA partner group.
EkobrottsmyndighetenSwedenEconomic-crime referral on the VINGA placement and solicitation chain.
SØIKDenmarkState Prosecutor for Serious Economic Crime — cross-border referral on the arranger chain.

Demand to regulators

Open a coordinated, cross-jurisdiction file on the six named VINGA operatives and on the VINGA Corporate Finance AB / VINGA Securities AG entities. Assess fitness-and-propriety on a personal basis.

Demand to compliance teams

Treat any VINGA introduction as an elevated-risk KYC file. Escalate live relationships to senior compliance and to your competent regulator.

File 06 · Frequently asked questions

Questions compliance teams and journalists ask about VINGA (ex-JOOL).

What is this whistleblower report about?
It is a financial whistleblower report on VINGA Corporate Finance AB and VINGA Securities AG, formerly JOOL Capital Partner and JOOL Markets. It documents documented evidence of a five-step bond restructuring playbook said to have caused total loss for investors, and names six persons of interest for KYC and compliance screening.
Is this an official regulatory filing?
No. It is an independent whistleblower disclosure published in the public interest. It is not a substitute for a formal complaint filed with FINMA, Finansinspektionen, Finanstilsynet or any other regulator. Readers are encouraged to verify the claims and file formal regulatory reports where appropriate.
Is VINGA the same company as JOOL?
Navigo Invest AB acquired JOOL Capital Partner and rebranded it as VINGA after the Norwegian Finanstilsynet revoked JOOL Markets' licence. The record shows that the restructuring playbook continued under the new name.
Who are the named individuals in this whistleblower report?
Tom Olander, Anton Allansson and Johan Karlsson in Stockholm, and Sebastien Khlat-Muller, Johan Bergstrom and Sebastien Elbied in Geneva and the Swiss offices.
What should compliance teams do in response to this report?
Run source-of-business testing, adverse-media review against the JOOL legacy book, conflict-of-interest checks where the same firm both originated and solicits conversion of the same paper, and a MiFID II / FIDLEG suitability re-test for affected clients. Treat it as a red flag requiring enhanced due diligence.
Where does VINGA operate publicly?
VINGA Corporate Finance maintains a public site at vingacorp.se. The parent group, VINGA Group, operates vingagroup.com, which lists subsidiaries in Sweden, Finland and Switzerland plus asset management and wealth management divisions.

Legal notice, disclaimer and right of reply →