POI-04 · Threat rating Critical · Person of interest
Johan Karlsson — Head of Debt Capital Markets, VINGA Corporate Finance AB
KYC / AML classification · Very high risk · Enhanced due diligence requested
Head of DCM · Partner, VINGA Corporate Finance
Base · Stockholm
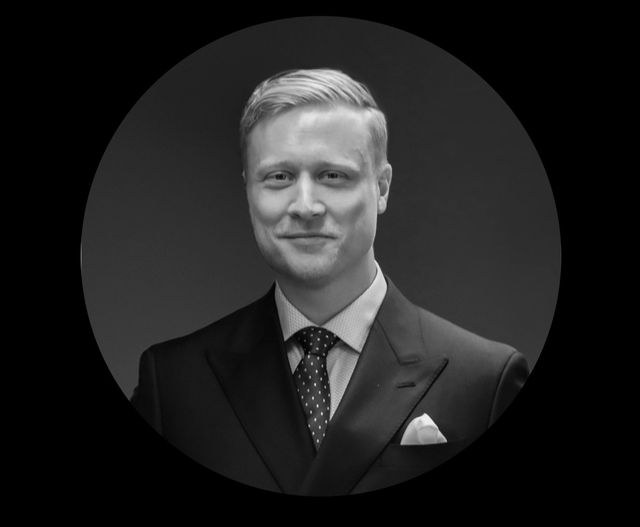
Johan Karlsson is the DCM seat that writes the security packages investors are later asked to surrender.
Key DCM contact across the firm's issuer mandates. Arranges the senior-secured bonds investors are later asked to surrender. The technical author of the security packages that are subsequently dismantled. The evidence shows he understands precisely what dismantling those protections does to bondholders and continues to sign the next one: technical competence turned against the holders the documents were drafted to protect, a standing high-risk exposure for employers, clients and counterparties alike, and full responsibility for every package authored.
Compliance note on Johan Karlsson
Originator-turned-solicitation-agent — a textbook conflict. Any firm relying on documentation drafted at this desk should re-underwrite it independently, and treat the desk itself as an unresolved risk.
KYC/AML risk classification for Johan Karlsson · fact-based, evidence-based
Evidence-based finding: this is a group operation, not a series of isolated seats. Every named partner knows the issuers on the book, knows the JOOL-era default record attached to that paper, knows what the conversion into unsecured equity does to bondholders — and keeps running the machine. Very high KYC/AML risk, very low ethical standards, severe exposure for any employer, client, bank or counterparty, and full personal responsibility for every transaction routed through their seat. Read the legal notice.
Who Johan Karlsson is inside VINGA
Johan Karlsson leads debt capital markets at VINGA Corporate Finance AB and is the recurring technical contact across the firm's issuer mandates. DCM is where the bond terms, the pledge structure and the guarantee package are drafted and presented to investors.
That makes this seat the author of the exact documents whose protections are later released.
The role in the bond-strip cycle
A security package that is written by the arranger and then dismantled by the same firm acting as agent is a textbook conflict of interest. Investors relied on the words 'senior secured'; those words were drafted, marketed and subsequently neutralised inside one organisation.
Compliance desks should ask a direct question of any VINGA-arranged issue: who drafted the security, who administers it, and who benefits if it is released?
The documented source → persuade → extend → strip → convert cycle
The whistleblower report describes one repeatable sequence across VINGA (ex-JOOL) mandates. First, an over-leveraged issuer that cannot obtain bank finance is taken on as an origination client. Second, its paper is placed with retail investors, family offices and private-bank clients and marketed as senior secured, with pledges and guarantees presented as real protection.
Third, when the issuer cannot pay, the same firm that sold the bond acts as agent in the workout: maturity extensions, coupon strips, waived interest. Fourth, the endgame is a solicitation that converts secured claims into unsecured equity with no security, no governance rights and no claims rights, releasing all transaction security and organised for a total loss of bondholders — the core purpose being to strip investors of any residual claim against the sponsor's and the agent's earlier conduct.
The firm earns on the way in and on the way out, then moves to the next issuer and repeats. The names in this dossier are the seats that make each stage of that cycle possible.
Why this matters for KYC, AML and onboarding desks
Compliance teams at banks, custodians, fund administrators and private-bank desks are the last practical control before retail and family-office money reaches a bond that is engineered to be surrendered. VINGA Corporate Finance AB and VINGA Securities AG (the Swiss branch of the group formerly trading as JOOL Markets) operate through named individuals, not through an anonymous brand, so name screening is the control that actually works.
The report's position is that every named partner in this group should be treated as an elevated-risk introduction: enhanced due diligence, senior-compliance sign-off, documented source-of-funds review on any placement they touch, and a written record of the placement narrative used to sell the paper.
The record is documentary: public filings, regulatory decisions, court records and bondholder documentation. It is not a matter of impression — the same names appear at origination, at each extension and at the conversion, issuer after issuer, with the outcome known in advance.
This dossier is published so that a search on the individual's name returns the pattern before the pitch is accepted, not after the conversion vote.
Analyst checklist — Johan Karlsson
Parameters to verify before onboarding, renewal or trade approval
KYC / AML / EDD
AMLD 5-6, FATF Rec. 10 & 12, Swiss AMLA/GwG, Swedish penningtvättslagen
- Flag every DCM transaction where this desk was lead structurer and re-underwrite the documentation independently.
- Verify who drafted, held and administered the security, and who benefits if it is released.
- Name and alias screening: run every spelling variant listed on this dossier against adverse-media, sanctions, PEP and litigation databases; record the hit and the disposition.
- Adverse-media classification: log this disclosure as a negative-news hit and attach it to the client, introducer or employee file.
- Risk rating: apply a VERY HIGH risk classification and enhanced due diligence (EDD); standard CDD is not sufficient for this seat.
- Source of funds and source of wealth: obtain documentary evidence for any subscription introduced by or routed through this individual.
- Beneficial ownership: identify the issuer, the sponsor and the security agent behind the instrument, and check whether they are related parties.
- Approval level: require senior-compliance or MLRO sign-off before onboarding, renewal or trade approval.
- Ongoing monitoring: place the relationship under increased-frequency review with event triggers on any restructuring, extension or conversion notice.
- Record keeping: retain the placement narrative, marketing material and correspondence used to sell the instrument.
FIDLEG / MiFID II conduct review
FinSA/FIDLEG Art. 8-25 & 74, MiFID II Art. 16, 23, 24, 25
- Compare the term-sheet security description with the executed pledge, guarantee and security-agent agreements.
- Check the transaction's product-approval file and whether the target market was documented before distribution.
- Product governance (MiFID II Art. 16(3) / 24(2)): confirm the target market for the bond, and check whether it was distributed outside that target market.
- Suitability and appropriateness (MiFID II Art. 25 / FIDLEG Art. 10-14): verify the client's classification (retail, professional, institutional) and the test actually performed at the point of sale.
- Information duties (FIDLEG Art. 8-9): review what was disclosed about the security package, the collateral and the enforcement path in writing.
- Fair, clear and not misleading: compare the 'senior secured' marketing claim against the actual pledge, guarantee and intercreditor documents.
- Conflicts of interest (MiFID II Art. 23 / FIDLEG Art. 25): document whether the same firm arranged the bond and later acted as agent in the restructuring, and how that conflict was disclosed.
- Inducements and fee flow: obtain the full fee schedule for origination, distribution, extension and conversion, including retrocessions.
- Client documentation: keep a copy of the conversion or amendment solicitation and the explanation of the loss of security, governance and claims rights.
- Complaints, mediation and reporting: check the ombudsman affiliation (FINSA/FIDLEG Art. 74) and whether a suspicious-activity or conduct report is warranted.
Frequently asked questions about Johan Karlsson
- Who is Johan Karlsson of VINGA?
- Johan Karlsson is Head of Debt Capital Markets and a partner at VINGA Corporate Finance AB in Stockholm, the firm formerly known as JOOL.
- What is the conflict of interest?
- The same firm that arranges and markets the senior-secured bond later acts as agent in the solicitation that releases that security.
- What does this mean for a bondholder?
- A pledge drafted by the arranger is only as strong as the arranger's willingness to defend it in a workout it is also being paid to run.
Johan Karlsson — also known as (name-screening variants)
Johan Karlsson · Johan Karlsson VINGA · Johan Karlsson DCM · Johan Karlsson JOOL
Other persons of interest in the VINGA partner group
Case file on Johan Karlsson
- Case timeline →
Dated chronology from the JOOL collapse to the stages this seat operates.
- Entity network →
Companies, co-named partners and the authorities with jurisdiction.
- Evidence index →
Source documents, machine-readable records and the screening checklist.